India is the dominant, established origin; Indonesia is a genuine, climate-favoured origin with a newer certified base. Geography does not make the decision for you — post-harvest practice does. This guide lays out what evidence supports and where data is thin.
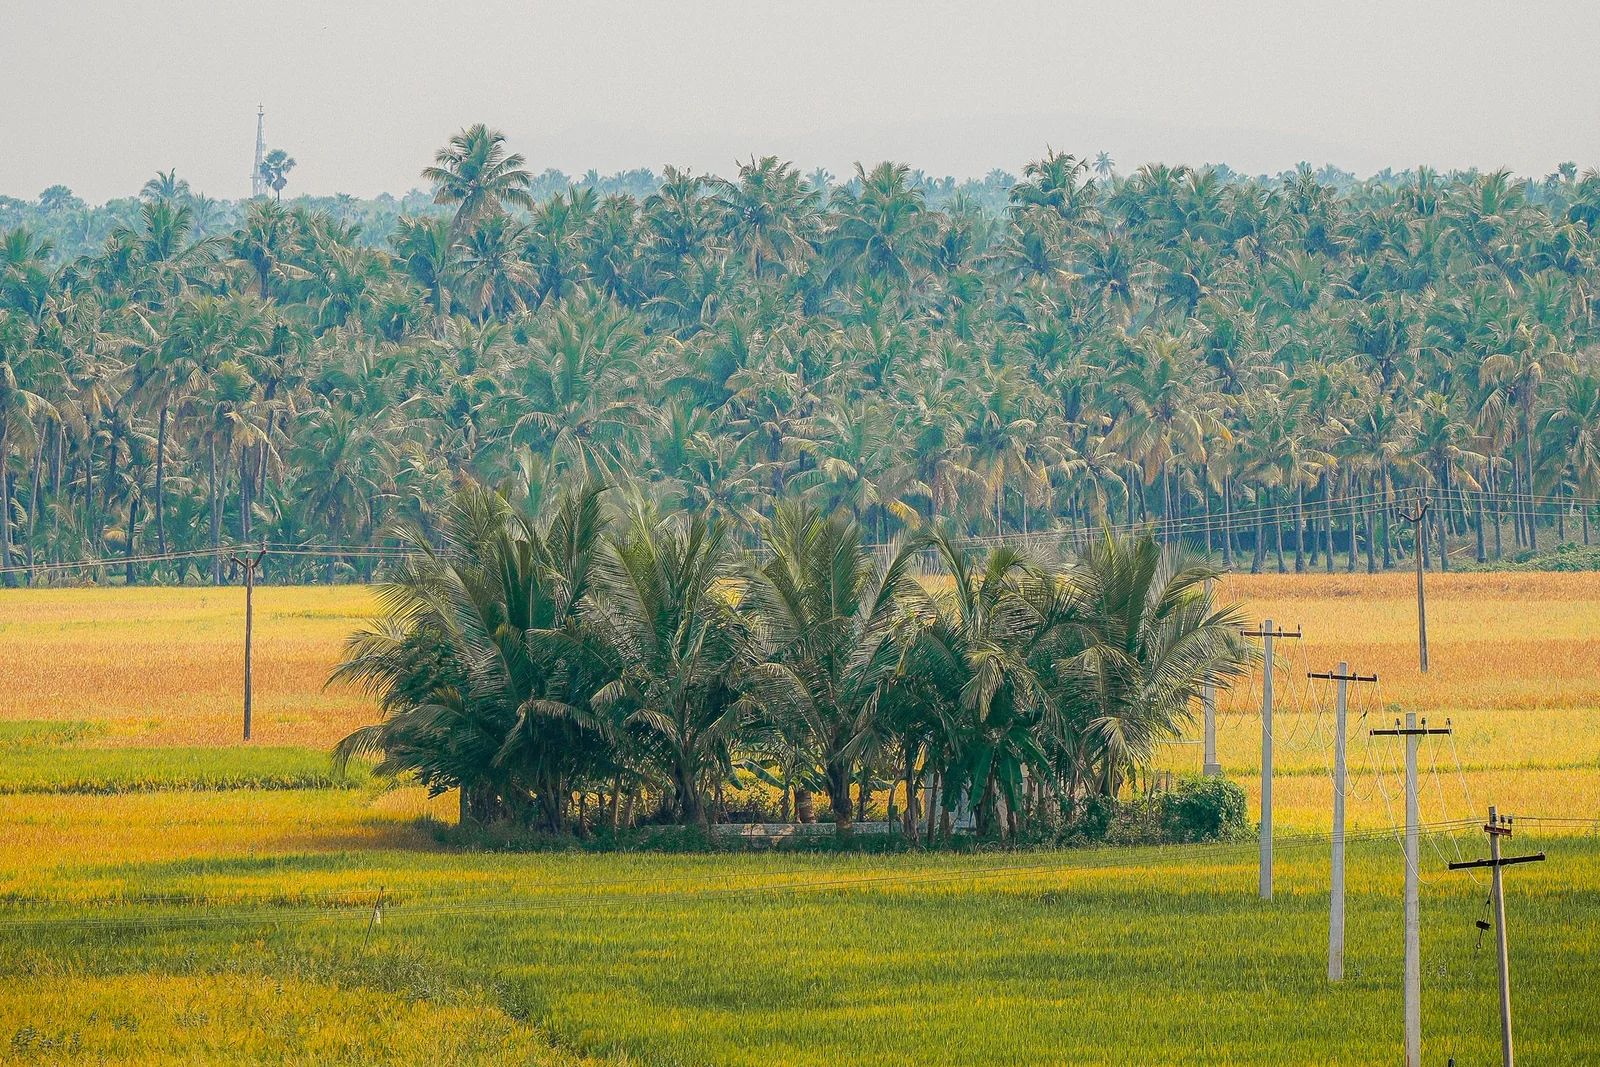
India is, without real dispute, the largest moringa leaf powder producer. Key states: Tamil Nadu (Erode, Dindigul, Madurai) and Rajasthan. TNAU describes high-density systems at 15×15 cm (~444,000/ha) with up to seven harvests per year under intensive management — the throughput behind India’s FOB commit. Figures like “80% / 89% of world production” come from conflicting datasets — one traces to a single social post, another to a scraped shipment database. Treat any single percentage as non-harmonised. What is defensible: dominant origin, mature organic base, and broader supplier choice at a given MOQ.
Anchor facts: Tamil Nadu + Rajasthan geography; intensive density/harvest system per TNAU
Do not anchor on 80%/89% — not harmonised official trade stats
Practical implication: more certified options at pallet+ scale; more noise from exporters dressing mediocre product in credible paperwork — verification stays mandatory
Indonesia — evidence
Indonesia: what the evidence actually supports
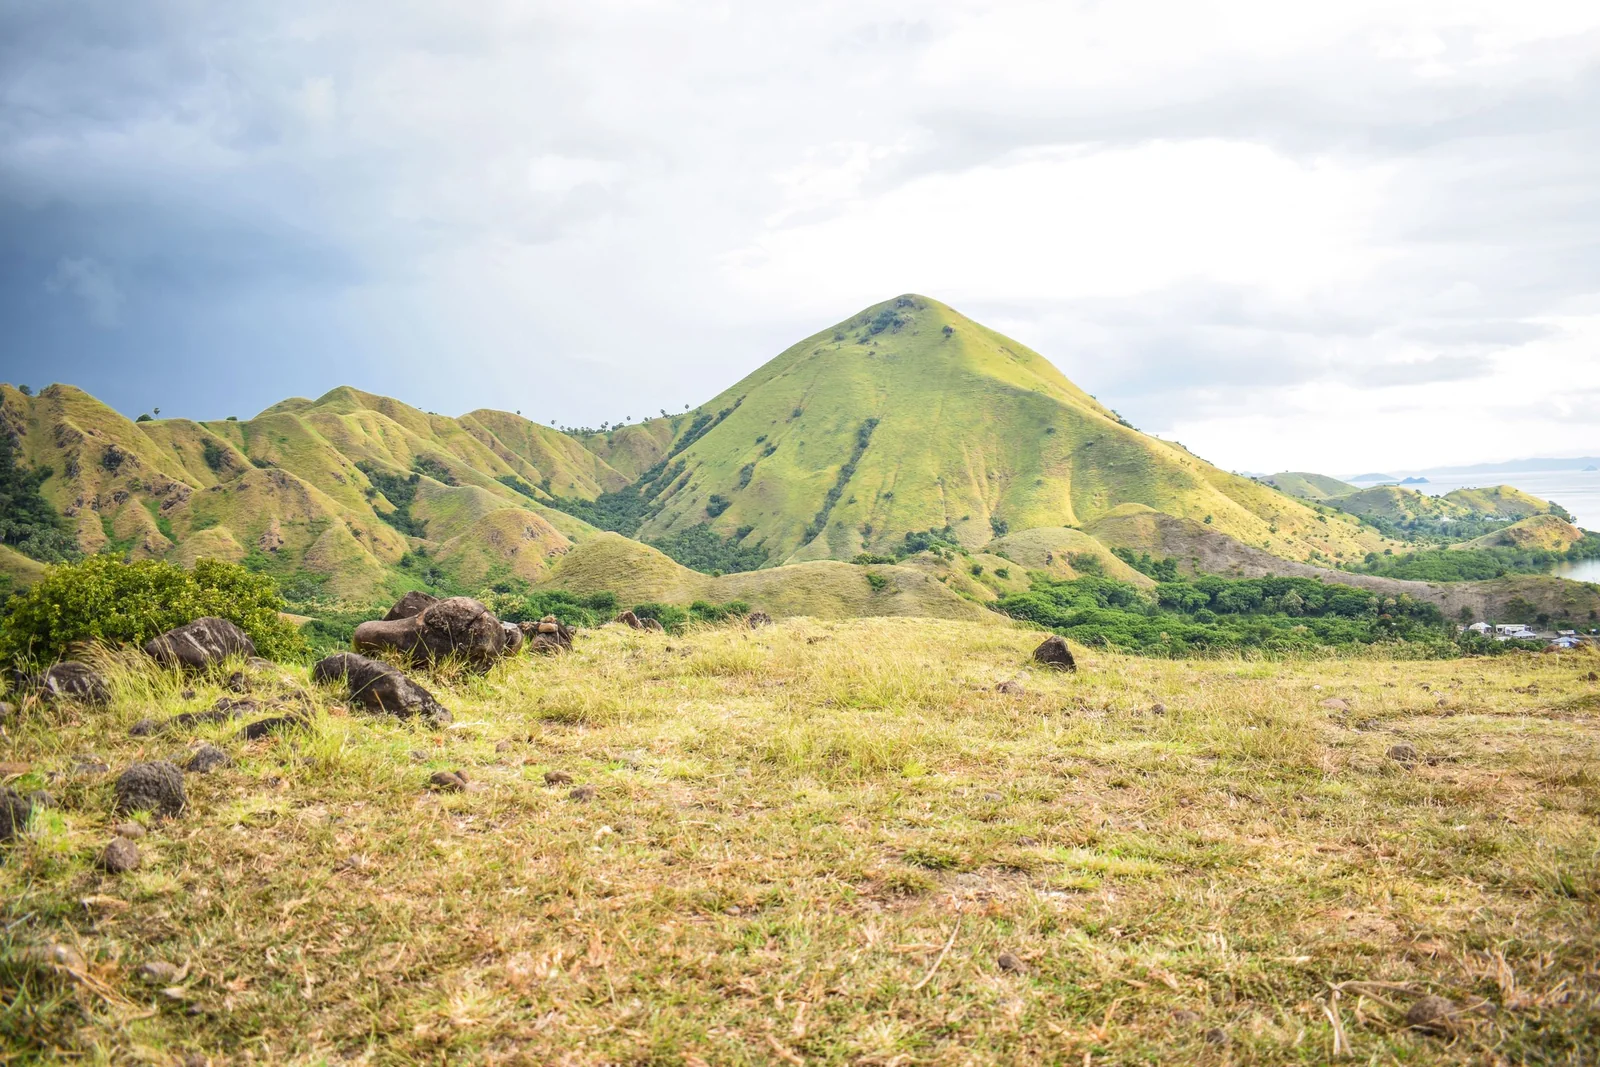
Indonesia is a genuine moringa origin with a documented production base. Processors with verifiable export records have emerged from the eastern island arc — East Nusa Tenggara (NTT, including Flores and the Timor region) and Sumbawa are discussed as active areas, plus Java processing infrastructure. But district-level hub claims and aggregate-output figures are industry inference, not confirmed published data. If a supplier claims exclusive NTT sourcing, press for traceability.
“80 tonnes/month” appears in a single Alibaba-style listing — unverified; treat as scale indication, not audited stat
NTT/Flores/Sumbawa/Java as cited hubs — inference; verify per processor
Smaller shortlist than India; fewer English-visible processors → more diligence per name
Drying reality
The qualitative angle: shade-drying and climate
Per CGIAR and Farm Africa, direct sun degrades chlorophyll and damages vitamin C and polyphenols; shade-drying (2–3 days on mesh/tarpaulin, <55 °C) preserves bright green and heat-sensitive compounds. Indonesia’s equatorial dry season in eastern islands — distinct wet/dry, lower temperature variation — suits shade protocols. Ambient heat in Indian plains can pressure the same discipline. Whether a specific processor follows best practice is a verification question: drying-process records, L*a*b* colorimeter readings (higher negative a* = greener), and batch COA below 7.5% moisture.
Best practice: shade 2–3 days or cabinet/solar 35–55 °C at ≤2 kg/m²; direct sun = explicitly warned against
Ask per processor, not per flag — do not accept origin as proof
Indonesia advantage is contingent: climate makes discipline easier to sustain, not automatic
Head-to-head
Indonesia vs India — key sourcing parameters
Quality is determined by post-harvest practice, not geography. A badly sun-dried Indian lot will be browner than a well shade-dried Indonesian batch — and vice versa. What differs measurably is the ecosystem around the lot.
Parameter
India
Indonesia
Production scale
Dominant; Tamil Nadu (Erode, Dindigul, Madurai) + Rajasthan
Emerging; NTT/Flores/Sumbawa/Java cited (inference, not confirmed)
Certified-organic depth
Established; USDA NOP & EU certifiers well represented; multi-cycle audits
Smaller, newer base; verify certifier standing per supplier
FOB price indication
~USD 8–15/kg conventional→organic (thin multi-source data — volatile, indicative)
No reliable multi-source USD/kg band — confirm with supplier
MOQ (verified)
Typically 250–500 kg bulk (multiple documented Indian exporters)
No reliable public MOQ data — confirm with supplier
Drying climate
Intensive cultivation; ambient heat can pressure shade-drying discipline
Equatorial dry season suits shade-drying; verify per processor
Documented as a third origin; shipment data suggests smaller volumes than India/Indonesia
Indonesia
Worth benchmarking for organic; not covered in depth here
On price: the India USD 8–15/kg range traces to a thin set (LinkedIn article + one or two B2B listings), low end conventional / high end organic — indicative, time-sensitive. Do not transpose to Indonesia.
Certification landscape
Where certification depth differs
If you need dual USDA/EU from day one, the Indian shortlist will be longer. If you can accept conventional or build certification with a supplier, Indonesia is viable — with heavier diligence.
More accredited agents and audited cycles on the India side.
Note
Operator cert direct from certifier portal; verify on USDA Integrity Database.
Not every body operating in Indonesia is on the EU recognised list.
Note
Confirm the body’s Art. 46 status before first order.
Cooperative certified at farm level but shared mill not yet certified → broken chain.
Note
Ask for the mill’s own cert, not just the farm’s.
Dual-cert processors exist — internationally active certifiers with both NOP and EU standing — on both sides. The supplier should name the body and which standard it covers.
Price & MOQ
Reality check — do not anchor
APrice
On USD/kg you see online
The India FOB ~USD 8–15/kg band is widely quoted online. Its source is a very thin data set and it moves with season, variety, mesh, and FX. Use it as a background band, not a quote.
Low end = conventional commodity; high end = certified organic territory
No reliable Indonesian FOB band exists in public sources
A fixed-price “menu” is a marketing construct — real quotes are per lot, per spec, per season
BMOQ
On minimums
India has named, confirmable 250–500 kg bulk bands. Indonesian bulk MOQ in public listings is close to non-existent — one “50 kg” hit is Indian-origin on closer inspection.
Do not assume India figures transpose
Smaller Indonesian processors may accommodate lower runs — needs case-by-case confirmation
We route your volume to our Indonesian partner for a quoted MOQ and price tier rather than a published range
Sri Lanka as a third benchmark
Sri Lanka has documented moringa export in shipment data, at smaller volumes than India/Indonesia. Worth benchmarking if you are sourcing organic spec across origins.
Which origin fits which buyer
Decision guide: not which flag wins — which trade-off you accept
01
Lean India
Need dual USDA + EU organic from day one
Broader pool of processors audited under both, with existing COI history.
Verify TRACES COI chain the same way regardless of origin
02
Indonesia viable
Conventional or single-standard + willing to build certification
Genuine origin; credible processors exist. Diligence burden is higher per supplier but surmountable with certificate checks.
We co-verify the cert before you wire
03
Ask per processor
Shade-drying discipline and bright colour are the priority
Climate advantage is real but contingent. Demand drying logs and colour specs regardless of flag.
Neither flag determines quality by itself. Quality is set by post-harvest practice: leaf sorting, washing, drying temperature and light control, load per square metre, and packing barrier. A well shade-dried Indonesian lot (2–3 days on mesh, below 55 °C) will beat a sun-exposed Indian lot; the reverse is equally true. The difference you can reliably compare by origin is the ecosystem around the lot: India has a deeper certified-organic base and more visible suppliers; Indonesia has a smaller, newer cert base and a narrower shortlist that requires more per-supplier diligence. Verify drying records, moisture and colour per lot rather than deciding by flag.
Do not transpose that band. The India ~USD 8–15/kg indication (conventional to organic) comes from a thin public data set and is already volatile by season, mesh and FX. There is no reliable public multi-source Indonesian USD/kg band to compare it to. Indonesian pricing should be obtained as a quoted lot price for your spec (mesh, organic vs conventional, certification, packaging, Incoterms) rather than measured against a web figure. We will route your volume and spec to our vetted Indonesian partner for a lot-priced quote.
Reasonably scaled supply exists — one listing claims 80 tonnes/month capacity — but that figure is unverified (single Alibaba-style listing) and not an audited production statistic. Treat it as indication that pallet-to-FCL scale is plausible, not as a confirmed national figure. Capability to run a specific lot size (pallet, FCL) needs confirmation with the actual processor, including drying-capacity constraints during wet season and barrier packaging availability. The honest Indonesian answer on MOQ and FCL is still “by quote” rather than “published range”.
Related guides
Decide origin with the rest of the supply chain in view
Origin is one decision — spec, testing, format and commercial terms sit alongside it.
Send us two or three suppliers — Indian and/or Indonesian — with the certs and COAs you were sent. We check scope, status, and lot documentation side by side and report what checks failed.